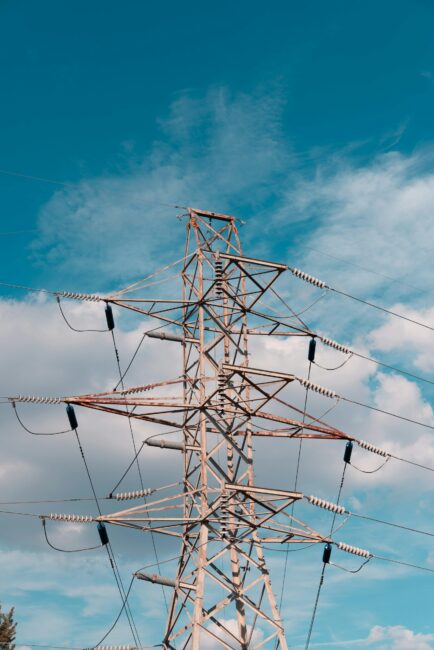
Transmission work drove MasTec's Power Delivery segment to 65% revenue growth. Source: Unsplash/benjamin lehman, Unsplash License.
Quick Answer: Coral Gables-based MasTec reported record third-quarter 2026 revenue of $5.15 billion, up 30% from a year earlier, and a record 18-month backlog of $24.5 billion, up 46%. Power Delivery led the growth with help from the newly acquired Superior Group. But pipeline permitting delays and weak Communications results led the company to cut its full-year profit guidance slightly while raising its revenue outlook to about $18.3 billion.
MasTec Inc., the infrastructure contractor that has its headquarters on South Douglas Road in Coral Gables, posted the largest quarter in its history on October 29, 2026. The company builds and maintains power lines, substations, renewable energy plants, pipelines and telecommunications networks, mostly in the United States and Canada. Its third-quarter results showed demand running well ahead of what management expected at the start of the year. They also showed how much it costs to turn that demand into profit when projects slip.
Revenue rose 29.9% to $5.152 billion, up from $3.967 billion in the third quarter of 2025. Adjusted EBITDA rose 30.2% to $486.4 million. The 18-month backlog, MasTec’s estimate of revenue it expects to earn from signed work over the next year and a half, reached $24.546 billion. That is up $7.8 billion from a year earlier and up about $3.2 billion from June 30. GAAP earnings per share still fell, and the company trimmed the profit side of its 2026 outlook. Shares fell more than 3% in after-hours trading after the release, according to Zacks Investment Research.
How much did MasTec’s revenue and earnings grow in Q3 2026?
MasTec called the quarter a revenue record. Chief Executive Jose Mas said in the release that both revenue and adjusted EBITDA came in ahead of the company’s own expectations. Revenue topped the Zacks consensus estimate of $4.94 billion by 4.3%. Adjusted earnings per share of $2.96 edged past the $2.94 consensus.
The gap between adjusted and GAAP results was wide. Operating income rose 10.4% to $275 million. Net income attributable to MasTec fell to $150.6 million from $160.7 million, and GAAP diluted earnings per share dropped 7.7% to $1.89 from $2.04. Adjusted net income, which strips out items such as acquisition-related costs and amortization, rose 26% to $253.2 million. Diluted share count rose to about 79.8 million from 78.6 million a year earlier.
| Metric | Q3 2026 | Q3 2025 | Change |
|---|---|---|---|
| Revenue | $5,152M | $3,967M | +29.9% |
| Operating income | $275M | $250M | +10.4% |
| Net income attributable to MasTec | $150.6M | $160.7M | -6.3% |
| GAAP diluted EPS | $1.89 | $2.04 | -7.7% |
| Adjusted diluted EPS | $2.96 | $2.48 | +19.3% |
| Adjusted EBITDA | $486.4M | $373.5M | +30.2% |
| Adjusted EBITDA margin | 9.4% | 9.4% | Flat |
| Operating cash flow | $267M | $89M | +200% |
| 18-month backlog | $24,546M | $16,780M | +46.3% |
Source: MasTec third-quarter 2026 earnings release (SEC Form 8-K, Exhibit 99.1). Percentage changes calculated from reported figures.
For the first nine months of 2026, revenue reached $13.355 billion, up about 28.9% from $10.359 billion a year earlier. Year-to-date operating cash flow more than doubled to $387.8 million from $173.0 million.
Which MasTec segments grew, and which lagged?
MasTec reports four main segments. In the third quarter, two of them delivered strong growth with stable or better margins. The other two showed the strains management described in its commentary. The segment revenue figures below add up to slightly more than consolidated revenue because intersegment eliminations and the company’s small “Other” segment are reported separately.
| Segment | Q3 2026 revenue | YoY change | Q3 2026 EBITDA | EBITDA margin (vs. Q3 2025) |
|---|---|---|---|---|
| Power Delivery | $1,835.2M | +65.2% | $241.5M | 13.2% (9.4%) |
| Clean Energy and Infrastructure | $1,825.9M | +33.9% | $149.3M | 8.2% (8.5%) |
| Communications | $806.9M | -11.8% | $54.0M | 6.7% (11.3%) |
| Pipeline Infrastructure | $724.1M | +21.1% | $75.1M | 10.4% (15.4%) |
Source: MasTec third-quarter 2026 earnings release; Zacks Investment Research.
Why did Power Delivery jump 65%?
Power Delivery covers transmission, distribution and substation work for electric utilities. It was the standout of the quarter and is now MasTec’s largest segment by revenue. Segment EBITDA more than doubled, rising 131.6% to $241.5 million, and its margin widened 380 basis points to 13.2%. Management credited both the legacy business and The Superior Group, the electrical contractor MasTec bought in July. Power Delivery backlog rose to $8.913 billion, up about 74% from $5.128 billion a year earlier and about 40% from $6.347 billion at the end of June.
How did Clean Energy and Infrastructure perform?
Clean Energy and Infrastructure includes renewable generation, other power generation and industrial and civil work. Revenue grew 33.9% to $1.826 billion, and EBITDA rose 29.3% to $149.3 million. The margin slipped 30 basis points to 8.2%. Backlog in the segment reached $8.315 billion, up about 65% from $5.026 billion a year ago, making it the second-largest pool of future work in the company.
What went wrong in Pipeline Infrastructure?
Pipeline revenue rose 21.1% to $724.1 million, but segment EBITDA fell 18.4% to $75.1 million and the margin dropped 500 basis points to 10.4%. Mas said in the release that permitting-related access delays on certain pipeline projects hurt margins. Zacks reported that the delays left crews and equipment underused. MasTec chose to keep experienced crews in place rather than release them. Mas said retaining those crews was critical given the industry investment ahead, and that construction has since begun and production is ramping. Demand did not weaken: pipeline backlog grew about 26% from the second quarter to $2.265 billion, up from $1.571 billion a year earlier.
Why is Communications shrinking?
Communications covers wireless, wireline and fiber network construction. It was the weakest segment, with revenue down 11.8% to $806.9 million and reported EBITDA down 47.6% to $54.0 million. Excluding $7.1 million in restructuring charges, adjusted segment EBITDA was $61.1 million, a 7.6% margin, compared with 11.3% a year earlier. Mas said certain customers deferred spending in the second half of 2026. In response, MasTec is reducing indirect costs, including exiting underperforming markets, and expects those steps to begin improving profitability in 2027. Communications backlog was essentially flat from a year earlier at $5.053 billion and down from $5.461 billion at the end of June. The release linked the segment’s longer-term opportunity to rising AI-driven data consumption.
How big is MasTec’s backlog now?
MasTec’s 18-month backlog of $24.546 billion is a company record. It is up 14.8% from the second quarter and 46.3% from the third quarter of 2025. Backlog stood at $19.0 billion at the end of 2025, according to the company’s fourth-quarter release in February. The year-to-date increase is about $5.5 billion.
| Segment backlog | Sept. 30, 2026 | June 30, 2026 | Sept. 30, 2025 |
|---|---|---|---|
| Power Delivery | $8,913M | $6,347M | $5,128M |
| Clean Energy and Infrastructure | $8,315M | $7,791M | $5,026M |
| Communications | $5,053M | $5,461M | $5,055M |
| Pipeline Infrastructure | $2,265M | $1,792M | $1,571M |
| Total | $24,546M | $21,391M | $16,780M |
Source: MasTec third-quarter and second-quarter 2026 earnings releases.
Power Delivery’s backlog gain includes work brought in by Superior, which joined during the quarter. Even so, the pattern across the table is broad. Three of the four segments posted double-digit sequential backlog growth, and only Communications declined.
What is The Superior Group, and how did MasTec pay for it?
MasTec agreed in July to buy Electrical Specialists, which does business as The Superior Group. The Real Deal reported a total price of about $1.7 billion: $1.2 billion in cash and $475 million in MasTec stock, plus a possible earnout tied to Superior’s performance over the three years after closing. Superior is an Ohio-based full-service electrical contractor founded in 1925, with more than 3,000 employees. In its second-quarter release, MasTec described Superior as a recognized leader in building data center infrastructure that also serves healthcare, entertainment and industrial markets. Superior expected 2026 revenue of $1.6 billion to $1.7 billion. MasTec said it expects Superior to add $2.2 billion to $2.5 billion in revenue next year. The deal closed in late July, the week before MasTec’s July 30 second-quarter release, and Superior CEO Bryan Stewart stayed in his role.
The purchase shows up clearly on the balance sheet. Net debt rose to $3.687 billion at September 30 from $1.935 billion at the end of 2025. Zacks put total debt, including finance leases, at about $4.17 billion, with cash of $481.8 million. The release also noted a smaller acquisition of a company specializing in pipeline infrastructure, intended to add capacity and project management expertise. Management told investors it expects 2026 operating cash flow above $1 billion and year-end leverage below 2 times, according to Zacks.
Did MasTec raise or cut its 2026 guidance?
MasTec did both. It nudged revenue guidance up and trimmed its profit outlook. Full-year revenue guidance is now about $18.3 billion, compared with about $18.2 billion in July and $17.0 billion in the initial outlook in February. Adjusted EBITDA guidance is now $1.565 billion to $1.600 billion, an 8.6% to 8.7% margin. That compares with about $1.6 billion, or an 8.8% margin, in July. Chief Financial Officer Paul DiMarco described the change as about 1% at the midpoint. He said that with less time left in 2026 to reach run-rate production, near-term margin recognition could be affected. Zacks reported that management expects some deferred revenue and earnings to shift into 2027.
| 2026 guidance item | Feb. 2026 (initial) | July 2026 | Oct. 2026 | 2025 actual |
|---|---|---|---|---|
| Revenue | $17.0B | $18.2B | ~$18.3B | $14.3B |
| Adjusted EBITDA | $1.45B | $1.6B | $1.565B-$1.600B | $1.15B |
| Adjusted diluted EPS | $8.40 | $9.30 | $8.92-$9.30 | $6.55 |
| GAAP diluted EPS | Not shown | $6.20 | $5.69-$6.01 | $5.07 |
| GAAP net income | Not shown | $539M | $498M-$524M | $422.0M |
Source: MasTec fourth-quarter 2025, second-quarter 2026 and third-quarter 2026 earnings releases; Zacks Investment Research. “Not shown” means the figure was not in the sources reviewed.
Subtracting nine-month revenue of $13.355 billion from the $18.3 billion full-year target leaves about $4.9 billion for the October-to-December period. Using the company’s rounded $14.3 billion 2025 revenue figure, last year’s fourth quarter was roughly $3.9 billion. That would make the implied gain about 25%, a growth rate in line with the year to date. Because the 2025 total is rounded, that comparison is approximate.
What do MasTec’s results mean for Miami-Dade business?
MasTec is headquartered in Coral Gables, in Miami-Dade County. It traces its roots to 1929, trades on the New York Stock Exchange under the ticker MTZ, and reported about 32,000 employees in its February 2026 release, before adding Superior’s roughly 3,000 workers. Its 2025 revenue of $14.3 billion is on track to grow to about $18.3 billion in 2026. The company is led by CEO Jose Mas and CFO Paul DiMarco, and its headquarters is at 800 South Douglas Road. Mas also co-owns Inter Miami CF with his brother Jorge Mas and David Beckham, according to The Real Deal.
The third-quarter results matter locally in several ways.
- A national business run from Coral Gables: MasTec’s earnings release does not break out Florida revenue. Its growth drivers, including utility grid spending, data center electrical work, renewable and other power generation, and pipeline capacity, are national in scope. Miami-Dade’s stake is mainly as the home of the decision-makers, not as the site of the construction.
- Data center and power demand: Through Superior, MasTec now has a sizable foothold in data center electrical construction. Power Delivery and Clean Energy now account for about $17.2 billion of the company’s $24.5 billion backlog. That spending is aimed at grid capacity and power-hungry digital infrastructure, the area where MasTec is now investing most heavily.
- Exposure to permitting risk: The pipeline margin squeeze shows that a record backlog does not translate directly into profit. Permitting and site-access timing can idle crews and equipment, and those costs land in the period when the delay happens.
The quarter’s signals were mixed. Revenue, backlog and cash flow all hit records, while GAAP earnings per share declined and profit guidance moved modestly lower. Communications, a long-standing MasTec business, is being restructured, while the electrical and power businesses expanded by acquisition are carrying growth.
Frequently Asked Questions
What was MasTec’s revenue in the third quarter of 2026?
MasTec reported record revenue of $5.152 billion for the quarter ended September 30, 2026, up 29.9% from $3.967 billion a year earlier.
How large is MasTec’s backlog?
Estimated 18-month backlog reached a record $24.546 billion at September 30, 2026. That was up 46.3% year over year and 14.8% from June 30. Power Delivery held the largest share at $8.913 billion.
Did MasTec change its 2026 guidance?
Yes. It raised revenue guidance to about $18.3 billion and lowered adjusted EBITDA guidance to $1.565 billion to $1.600 billion. Adjusted EPS guidance is now $8.92 to $9.30, compared with $9.30 previously. Pipeline permitting delays were the main reason cited.
Why did MasTec’s GAAP earnings per share fall?
GAAP diluted EPS fell to $1.89 from $2.04. Net income attributable to MasTec declined while the diluted share count rose to about 79.8 million. Adjusted EPS, which excludes items such as acquisition-related costs, rose 19.3% to $2.96.
What is The Superior Group?
It is an Ohio-based electrical contractor founded in 1925, with more than 3,000 employees and a focus on data center and mission-critical infrastructure. MasTec acquired it in July 2026 for about $1.7 billion in cash and stock.
Sources and Further Reading
- MasTec Reports Third Quarter 2026 Results and Updates Full Year 2026 Financial Guidance (Form 8-K, Exhibit 99.1) — MasTec Inc. / U.S. Securities and Exchange Commission
- MasTec Second Quarter 2026 Earnings Release (Form 8-K, Exhibit 99.1) — MasTec Inc. / U.S. Securities and Exchange Commission
- MasTec Reports Fourth Quarter and Full Year 2025 Financial Results and Provides Initial 2026 Guidance — MasTec Inc. via Business Wire
- MasTec Q3 Earnings, Revenues Beat Estimates on Power Delivery Strength — Zacks Investment Research
- MasTec Acquiring The Superior Group in $1.7 Billion Deal — The Real Deal
- MasTec, Inc. (MTZ) Company Profile — Stock Analysis
About the Author